
 Facebook
 X
 Pinterest
 Copy Link
Thinking About Selling Your Home in 2027? Here’s What to Do Now
November 17, 2026 | Milton, Quincy, Dorchester, Greater Boston & South Shore Real Estate
Thinking about selling your home in 2027? You might be surprised by how much you can accomplish before the new year, without putting your house on the market or making any big decisions just yet.
With the holidays approaching, most of us are focused on family gatherings, shopping, and everything else that comes with this busy time of year. Selling a home might not be at the top of your list.
However, if moving is even a possibility next year, now is a great time to start thinking about your options.
Quick Answer: When Should You Start Preparing to Sell Your Home?
Ideally, start planning several months before you want to list. This gives you time to understand your home’s value, decide which improvements are worth making, organize your finances, and figure out where you’ll go next. You don’t need to be ready to sell to start the conversation.
1. Find Out What Your Home Is Worth
Before you start painting walls or replacing appliances, it’s helpful to know what your home might sell for in today’s market.
A comparative market analysis (CMA) looks at recent sales, current competition, and how your home compares to similar properties.
It can also help you understand how much equity you may have available for your next purchase.
Of course, your home’s value may change between now and when you’re ready to list. Still, having a starting point can make planning much easier.
2. Decide Which Improvements Are Worth Making
Not every home needs a new kitchen or bathroom before going on the market.
In fact, some of the most effective preparations are relatively simple:
- Fresh paint where needed
- Minor repairs you’ve been putting off
- Decluttering and organizing
- Cleaning up landscaping
- Improving lighting and presentation
Before spending money on larger projects, talk with a real estate professional about what buyers in your price range are looking for.
The goal isn’t to make your home perfect. It’s to make smart decisions about where your time and money will have the greatest impact.
For additional perspective, the National Association of REALTORS® Remodeling Impact Report explores how different improvements may affect homeowner satisfaction and resale value.
3. Start Decluttering Before You’re Ready to Move
This might be my favorite piece of advice because it’s something you can start doing right now.
Over the holidays, many of us are already cleaning, organizing, and making room for guests.
Why not use that momentum?
Start with one closet, the basement, or an area you’ve been meaning to tackle.
You don’t need to pack up your entire house. Just begin sorting through the things you no longer need.
You’ll appreciate having less to do when it’s time to get your home ready for photos and showings.
Thinking of Selling This Spring? Why a Pre-Listing Walk-Through Matters
4. Think About Where You’re Going Next
This is especially important if you’re selling one home to buy another.
Maybe your family has outgrown your current house, but you love living in Milton and don’t want to leave the community.
Or perhaps you’re thinking about downsizing and aren’t sure what your options look like.
Either way, it’s worth exploring what’s available before making decisions about selling.
Ask yourself:
- What isn’t working in my current home?
- What would I want in my next home?
- Do I need to sell before I can buy?
- What monthly payment would I be comfortable with?
- How flexible is my timeline?
For homeowners who have a low mortgage rate, this conversation can be particularly important.
You may have built substantial equity, but that doesn’t automatically mean your next monthly payment will be comfortable.
Understanding the numbers early can help you make a decision that works for your family.
5. Create a Timeline That Works for You
One of the biggest misconceptions about selling is that you need to have everything figured out before reaching out to an agent.
You really don’t.
Some homeowners want to move in the spring. Others are thinking about summer, when school is out. And some simply know that their current home isn’t meeting their needs anymore.
Your timeline should reflect your priorities.
For families who need to coordinate buying and selling, having a plan early can make a complicated process feel much more manageable.
And if the right home comes along sooner than expected, you’ll be better prepared to explore your options.
Is November Too Early to Start Planning for a 2027 Sale?
Not at all.
In fact, November can be a great time to have an initial conversation.
There’s no pressure to list immediately, and you can use the next few months to make decisions at your own pace.
Whether you’re planning to move up, downsize, or relocate, understanding your options now gives you more flexibility later.
Bottom Line
If you’re considering selling your home in 2027, you don’t have to wait until the new year to get started.
A little planning now can help you avoid unnecessary expenses, understand your options, and feel more prepared when the time comes.
And remember, starting the conversation doesn’t mean you’re committing to sell.
If you’re thinking about making a move in Milton, Quincy, Dorchester, or the surrounding communities, I’m always happy to help you figure out where to begin.
Is It Better to Buy or Sell a Home Before the Holidays?
November 4, 2026 | Milton, Quincy, Dorchester, Greater Boston & the South Shore Real Estate Market
Should you buy or sell a home before the holidays, or is it better to wait until the new year?
Now that November is here, holiday plans, family gatherings, and busy schedules are starting to fill our calendars. For many people, real estate takes a back seat. However, this time of year can offer some unexpected opportunities for both buyers and sellers.
Quick Answer: Should You Wait Until After the Holidays?
You don’t necessarily need to wait until spring to buy or sell a home. The holiday season often brings fewer listings and fewer active buyers. However, those who remain in the market may have a strong reason to make a move. The best timing depends on your goals, your local market, and how ready you are.
What Happens to the Real Estate Market During the Holidays?
Traditionally, real estate activity slows as we approach Thanksgiving and the December holidays.
People travel, spend time with family, and focus on year-end commitments. As a result, fewer homes may come on the market, and some buyers pause their searches.
According to the National Association of REALTORS®, housing activity changes throughout the year.
But slower doesn’t mean stopped.
There are still buyers looking and homeowners who need or want to sell. In fact, a quieter market can sometimes work in your favor.
Why Buying a Home Before the Holidays Can Make Sense
If you’re thinking about buying, don’t automatically rule out November or December.
Here are a few potential advantages:
- Less competition: With some buyers taking a break, you may face fewer competing offers.
- More room to negotiate: Depending on the property, sellers may be open to discussing price, closing dates, or other terms.
- Motivated sellers: Some homeowners have a specific reason for wanting to close before year-end.
Of course, there’s a trade-off. With fewer homes coming on the market, you may have fewer choices.
Also, mortgage rates still matter. You can follow current trends through Freddie Mac’s Primary Mortgage Market Survey.
The key is being prepared so you can recognize the right opportunity when it comes along.
Why Selling a Home Before the Holidays Can Work
You might think nobody wants to move during the holidays, but that’s not always the case.
While there may be fewer buyers, those actively searching often have a reason to move.
Maybe they’re relocating for work, their current home no longer fits their needs, or they’re hoping to settle in before the new year.
Plus, fewer competing listings can help your home stand out.
That doesn’t mean every home will sell quickly. Pricing, condition, and presentation still matter. And because schedules get busy, flexibility with showings can make a difference.
For some sellers, waiting until spring makes sense. For others, listing now may be the better choice.
What Does This Mean for Buyers and Sellers in Milton?
This is where I think having a plan matters more than following the calendar.
I work with many families who are looking to move from their first home into something larger. Often, they’re trying to figure out how to coordinate selling one home while buying another.
A quieter season may offer opportunities, but it can also mean fewer homes to choose from.
The same goes for homeowners thinking about downsizing. Some want to make a move before another winter. Others would rather enjoy the holidays and start fresh in the spring.
Neither approach is wrong.
In Milton, Quincy, and the surrounding communities, I always encourage clients to look at what’s happening in their specific price range rather than relying only on national headlines.
If you’re considering a move, my earlier blog on what today’s buyers and sellers really want in 2026 is another helpful place to start.
Bottom Line
So, is it better to buy or sell a home before the holidays?
There isn’t one answer for everyone.
The holiday market can be quieter, but that can create opportunities. Buyers may face less competition, while sellers may benefit from fewer competing homes.
The most important thing is understanding your options and choosing a timeline that works for you.
If a move is on your mind, whether it’s before the holidays or sometime next year, I’m always happy to talk through what makes the most sense for your situation.
The American Dream of Homeownership Is Changing, but It’s Still Going Strong
Owning a home is still a big part of the American Dream, but how people get there is changing.
According to Coldwell Banker’s 2026 American Dream Report, 85% of Americans still consider homeownership part of the American Dream. That’s encouraging, especially given the affordability challenges so many buyers are facing today.
One finding that really caught my attention? More families are thinking about homeownership across generations. In fact, 82% of parents with children ages 5 and under have considered or already started saving for their child’s future down payment.
For many families, saving for a first home is becoming part of long-term financial planning, much like saving for college.
What Does This Mean for Buyers in Milton and the South Shore?
We all know that buying a home in today’s market isn’t always easy. Between home prices, mortgage rates, and saving for a down payment, there can be some real obstacles.
But there’s also no single path to homeownership.
Some buyers are saving on their own, others are receiving help from family, and some are adjusting their timelines or considering different locations and types of homes.
What matters most is understanding your options and having a realistic plan that works for you.
Whether buying a home is something you’re hoping to do soon or a goal that’s still a few years away, I’m always happy to help you explore what’s possible.
Want to learn more?
Read the full Coldwell Banker article, The American Dream Has Become a Multi-Generational Plan, for more findings from the 2026 American Dream Report.
Should You Buy a Home Now or Wait for Mortgage Rates to Drop?
October 28, 2026 | Milton, Quincy, Dorchester, Greater Boston & the South Shore Real Estate Market
Should you buy a home now or wait for mortgage rates to drop? It’s a question I’m hearing from buyers, and I completely understand why.
Buying a home is a big financial decision. Nobody wants to buy today only to see interest rates drop a few months later.
But here’s another question worth asking: What happens if rates drop and suddenly more buyers are competing for the same homes?
There may also be another option you haven’t considered: negotiating seller concessions to help lower your mortgage payment during the first few years.
Let’s talk about it.
Quick Answer: Is It Better to Buy Now or Wait?
Waiting for lower mortgage rates could reduce your monthly payment, but it could also mean facing more competition or higher home prices. Buying now may offer negotiating opportunities, including seller concessions toward a temporary mortgage rate buydown.
The best decision depends on your budget, the homes available, and whether you’re comfortable with the monthly payment today.
What’s Happening With Mortgage Rates in October 2026?
Mortgage rates have been moving around quite a bit, and predicting where they’ll go next isn’t easy.
According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was 7.32% as of October 22, 2026.
Inflation, economic conditions, and global uncertainty can all influence mortgage rates. Even when the Federal Reserve changes its benchmark interest rate, mortgage rates don’t necessarily move in the same direction.
That’s why I encourage buyers to focus on what they can control rather than trying to predict exactly when rates will fall.
What Happens to Home Prices If Mortgage Rates Drop?
This is the part of the conversation I think deserves more attention.
There are buyers who would love to purchase a home but have decided to wait for more favorable interest rates.
If rates drop, some of those buyers may return to the market.
And if more buyers are competing for the same number of homes, what happens?
We could see more multiple-offer situations, less negotiating room, and potentially higher home prices.
Here in Milton, Quincy, and throughout the South Shore, we’ve seen how competitive the market can become when a desirable home is priced well.
Of course, lower rates don’t guarantee higher prices. Inventory, economic conditions, and local demand all play a role.
But waiting for a lower interest rate doesn’t necessarily mean you’ll get a better deal.
Let’s Look at a $900,000 Home
Imagine you’re considering a $900,000 home with a 20% down payment.
You have two options: buy now or wait and hope rates come down.
Here’s a hypothetical comparison using a 30-year fixed mortgage.
BUY NOW
Purchase Price: $900,000
Down Payment (20%): $180,000
Mortgage Rate: 7.40%
Monthly Principal & Interest: $4,985
WAIT
Purchase Price: $945,000
Down Payment (20%): $189,000
Mortgage Rate: 6.50%
Monthly Principal & Interest: $4,778
In this example, waiting results in a monthly payment that’s about $207 lower.
Sounds good, right?
But the buyer also pays $45,000 more for the home and needs an additional $9,000 for the down payment.
And there’s no guarantee prices will increase by 5%, or that mortgage rates will fall to 6.50%. These numbers are simply meant to illustrate why it’s important to look at the entire picture.
The interest rate matters, but so does the price you pay for the home.
What Is a Mortgage Rate Buydown, and How Could It Help?
Here’s something many buyers don’t realize.
In certain situations, you may be able to negotiate a seller concession that helps reduce your mortgage payments for the first few years.
It’s called a temporary mortgage rate buydown.
Two common options are a 2-1 buydown and a 3-2-1 buydown.
How Does a 2-1 Buydown Work?
With a 2-1 buydown, your monthly payment is temporarily reduced for the first two years.
If your actual mortgage rate is 7.40%:
- Year 1: Your payment is based on 5.40%.
- Year 2: Your payment is based on 6.40%.
- Year 3 onward: You pay based on the full 7.40% rate.
How Does a 3-2-1 Buydown Work?
A 3-2-1 buydown spreads the temporary payment reduction over three years.
Using that same 7.40% mortgage rate:
- Year 1: Your payment is based on 4.40%.
- Year 2: Your payment is based on 5.40%.
- Year 3: Your payment is based on 6.40%.
- Year 4 onward: You pay based on the full 7.40% rate.
The actual mortgage interest rate doesn’t change. Instead, money is set aside upfront to temporarily subsidize your payments.
And depending on the loan program and negotiations, the seller may be able to contribute toward that cost.
Not every mortgage qualifies for these programs, and seller contribution limits apply. Your lender can explain what’s available for your specific situation.
What Would a 3-2-1 Buydown Look Like on a $900,000 Home?
Let’s use our $900,000 example again, with 20% down and a $720,000 mortgage at 7.40%.
| Payment period | Payment rate | Approx. monthly payment |
|---|---|---|
| Year 1 | 4.40% | $3,605 |
| Year 2 | 5.40% | $4,043 |
| Year 3 | 6.40% | $4,504 |
| Year 4 onward | 7.40% | $4,985 |
That’s a difference of approximately $1,380 per month during the first year!
Now imagine negotiating with a seller to contribute toward that temporary buydown instead of asking for a price reduction.
Depending on the circumstances, that could be a strategy worth considering.
One important thing to understand: You still need to qualify for the mortgage based on the lender’s requirements, and you should be comfortable with the full payment once the buydown ends.
Temporary buydowns also have an upfront cost, so it’s important to compare the total cost and benefits with other options.
You can learn more about these programs through Fannie Mae’s temporary interest rate buydown guidelines.
Is It Better to Negotiate a Lower Price or a Seller Concession?
This is where having a strategy can make a difference.
Sometimes a seller may be more willing to offer a closing cost credit than reduce the asking price.
That credit could potentially help cover closing costs or fund a temporary rate buydown.
Other times, negotiating a lower purchase price may be the better financial decision.
There’s no one-size-fits-all answer.
It depends on the property, how long it’s been on the market, the seller’s motivation, and your financing.
And not every home will offer the same opportunity to negotiate.
What If You Buy Now and Mortgage Rates Drop Later?
Refinancing may be an option if rates decrease in the future.
But I always caution buyers against making a purchase based on the assumption that they’ll be able to refinance.
Rates may not fall as expected, refinancing comes with costs, and your financial situation could change.
If refinancing becomes an attractive option later, great!
But the home and monthly payment should make sense for you today.
Should You Wait Until Spring 2027 to Buy?
Spring typically brings more homes to the market, which can mean more choices for buyers.
But it can also bring more competition.
If you’re financially prepared and find a home that checks the right boxes this fall or winter, it may be worth exploring your options rather than automatically waiting until spring.
On the other hand, if you need more time to save, improve your financial position, or figure out where you want to live, waiting may be exactly the right decision.
The calendar shouldn’t make that decision for you.
Frequently Asked Questions About Mortgage Rates and Buying a Home
Will mortgage rates drop in 2027?
No one can predict mortgage rates with certainty. Inflation, the economy, Treasury yields, and global events can all influence where rates go. It’s best to make your homebuying decision based on what you can comfortably afford rather than relying on a specific future rate.
Is a 2-1 mortgage buydown worth it?
A 2-1 buydown can be helpful if you want lower payments during your first two years of homeownership, particularly if the seller contributes toward the cost. However, it’s important to compare the upfront expense and understand what your payment will be afterward.
Can a seller pay for a 3-2-1 buydown?
Yes, seller-funded temporary buydowns may be allowed with eligible mortgage programs, subject to lender requirements and seller concession limits. Your lender can confirm whether a 3-2-1 buydown is available for your loan.
Will home prices increase if mortgage rates decrease?
They could. Lower mortgage rates may encourage more buyers to enter the market, increasing competition. However, prices also depend on housing inventory, local demand, and broader economic conditions.
Is fall a good time to buy a home in Milton, MA?
Fall can offer opportunities for buyers, particularly when a property has been on the market longer or a seller is motivated. However, desirable homes can still be competitive. The best approach is to evaluate each property and your individual financial situation.
The Bottom Line: Don’t Focus Only on the Interest Rate
If there’s one thing I want buyers to take away from this conversation, it’s this:
Don’t let the interest rate be the only thing driving your decision.
The purchase price, monthly payment, competition, available inventory, and opportunities to negotiate all matter.
Sometimes waiting makes sense. Sometimes buying now with the right strategy can put you in a better position.
If you’re considering buying in Milton, Quincy, Dorchester, or anywhere in Greater Boston and the South Shore, I’m always happy to talk through your options and help you understand what’s happening in our local market.
No pressure, just a conversation.
Becky Davis, REALTOR®
Coldwell Banker Realty
📲 781.844.1413
✉️ becky.davis@cbrealty.com
🌎 beckydavisrealestate.com
📍 60 Adams Street, Milton
@beckydavisrealestate
Mortgage payment examples are for educational purposes only and assume a 30-year fixed mortgage with 20% down. Payments exclude property taxes, insurance, HOA fees, and other expenses. Actual rates, loan eligibility, seller concessions, and buydown terms vary.
Buying Before Selling a Home in Massachusetts: What Are Your Options?

Buying before selling a home in Massachusetts can feel a little like a chicken-and-egg situation.
Do we sell first? What if we sell and can’t find anything? Can we buy first? What happens if we find the perfect house before ours is even on the market?
These are conversations I have with clients all the time, and the answer isn’t the same for everyone.
In fact, I’ve helped clients navigate this in several completely different ways. Some have bought first and sold later. Some have needed a home sale contingency. Some have successfully lined up a sale and purchase at the same time. Others have sold first and rented while deciding what came next.
And right now, I’m working with clients who aren’t doing any of those things yet. They know exactly where they want to go, so we’re getting their current home ready and waiting for the right house to come along.
There isn’t one right way to do this.
The goal is to figure out which option makes the most sense for you.
Quick Answer: Can You Buy Before Selling Your Home in Massachusetts?
Yes. There are several ways to approach buying before selling a home in Massachusetts.
You may be able to buy first, potentially using a bridge loan. You can make your purchase contingent on selling your current home. You can sell first and buy later. You can try to coordinate both transactions at the same time. Or you can prepare your current home for sale and wait until the right property comes along.
Your finances are obviously a big part of the decision, but they’re not the only part. The market you’re selling in, the market you’re buying in, what you’re looking for and how comfortable you are with some uncertainty all matter too.
Option 1: Buy First and Sell Later
For a lot of homeowners, this sounds like the ideal scenario.
Find the house you love, buy it, move in and then deal with selling your current home.
I’ve had clients do this in a couple of different ways.
One set of clients used a bridge loan to buy their next home before selling their condo. We hoped we could get the condo sold and line everything up fairly closely.
The market had other ideas.
Their condo took longer to sell than we anticipated, so they ended up owning both homes for a couple months. Thankfully, they had planned for that possibility from the beginning.
I’ve also worked with clients who spent quite a while searching for their dream home. They were financially comfortable buying first, so once they finally found it, there was no reason to rush their existing home onto the market at a less-than-ideal time. They moved into the new house and waited for a better window to sell.
That’s the biggest advantage of buying first: flexibility.
You’re not selling your house and hoping the right next house appears before you need to move.
Of course, that flexibility can come at a cost.
Bridge loans are generally short-term financing and can be more expensive than traditional mortgage financing. They can also be harder to qualify for. And whether you’re using bridge financing or simply qualifying to carry both properties, you need to be comfortable with what happens if your current home doesn’t sell as quickly as you hoped.
For some people, that flexibility is absolutely worth it.
Option 2: Buy With a Home Sale Contingency
Sometimes people know from the beginning that they’ll need to sell their current home in order to buy.
And sometimes they don’t.
I recently worked with clients who started their search believing they could buy first. Partway through the process, it became clear that selling their current home needed to become part of the plan.
Fortunately, we were able to work out a home sale contingency with the seller.
Problem solved, right?
Well…sort of.
Now we actually needed to sell their house.
First, a seller has to be willing to accept a home sale contingency. https://www.mass.gov/info-details/re89r14-purchase-and-sale-agreement-in-residential-transactions?utm_source=chatgpt.comDepending on how competitive the property is, that isn’t always easy. If a seller has another buyer who doesn’t have a home to sell, that offer may feel like the safer choice.
But every situation is different.
The price matters. How long the home has been on the market matters. The competition matters. The rest of your offer matters. Even how prepared your current home is to hit the market can matter.
I’ve absolutely seen home sale contingencies work.
Then comes the next challenge: finding a buyer for your home and getting everything to line up.
Now your sale affects your purchase.
Closing dates matter. Financing dates matter. Your buyer’s terms matter. Sometimes we’re negotiating a few extra days here or moving a date there just to make the puzzle fit together.
It’s doable, but it’s no easy feat.
Option 3: Sell First and Figure Out What’s Next
Financially, selling first can be the cleanest option.
You know what you’re walking away with from your sale, and when you are ready to buy, you don’t have another home that still needs to sell.
But there’s an obvious question:
“Where am I going to live?”
Sometimes the answer is easier than you’d think.
I worked with a younger couple who had bought a home in the suburbs and realized they really missed city living. Instead of immediately trying to figure out where and what they should buy next, they sold their house, moved back into the city and rented.
It gave them some breathing room to figure out what they actually wanted their next move to look like without rushing into another purchase.
For someone else, selling first could mean staying with family, using a vacation property, finding a short-term rental or calling in a very big favor from some very nice friends.
The bigger question is whether you’re comfortable not knowing exactly how long that in-between period might last.
If you’re looking for something very specific, it could take a while.
But selling first can also give you something valuable: time to make your next decision without your current house dictating it.
Sometimes that’s exactly what someone needs.
Option 4: Sell and Buy at the Same Time
This is what a lot of homeowners hope to do.
And yes, it really can work.
I worked with clients who were selling and buying in the same town. We got their current house completely ready for market, but didn’t put it up for sale yet.
Then they found the house they wanted.
We got their offer accepted, immediately launched their current home, found a buyer and worked to get all of the dates and details of both transactions lined up.
They went from one home to the next, which is exactly what we had hoped would happen.
But there was a lot of preparation behind the scenes that made that possible.
We didn’t wait until they found their new house to start thinking about getting their current one ready. We had already done that work.
You’re also dealing with two separate transactions and two different sides of the market.
Maybe your current home sells in a weekend, but there are hardly any homes available that you want to buy.
Or maybe you find the perfect house immediately, but it takes longer than expected to find the right buyer for yours.
Even once both homes are under agreement, we’re coordinating buyers, sellers, lenders, attorneys, inspections, appraisals and closing dates.
When everything lines up, it’s great.
I just still like to have a Plan B in case one side doesn’t cooperate with our beautifully organized calendar.
Option 5: Get Ready Now and Wait for the Right House
This is an option I don’t think gets talked about enough.
You don’t necessarily have to do anything yet.
I’m working with clients right now who have been thinking about selling and moving up for the last couple of years.
But they’re happy where they are, and they know exactly where they want to go.
It’s a very specific and popular location, so selling their current home first doesn’t make a lot of sense for them. They could sell and then wait months for the right property to become available.
Instead, we’re playing the long game.
We’ve met a few times, talked about their current home’s value and what they’ll need to do to get it ready, and now they’re preparing the house for photos.
They’re not putting it on the market tomorrow.
They’re getting ready so that when the right house does come along, we’re not starting from scratch.
We can move quickly on the purchase and be in a position to put their current home on the market almost immediately if that’s what the situation calls for.
I really like this approach for someone who doesn’t need to move and only wants to do it for the right house.
It requires patience.
But sometimes the best move isn’t to force the timing.
It’s to be ready.
So How Do You Decide When Buying Before Selling a Home in Massachusetts?
This is where the financial piece and the real estate piece need to come together.
Before you start seriously looking, it’s helpful to understand what’s actually possible financially. Talking with a lender early can help you understand your buying power and financing options before the right house comes along.
Maybe buying first is completely comfortable. Maybe bridge financing opens up another option. Or maybe you technically could carry two homes, but the thought of two mortgage payments for several months would keep you up at night.
That matters too.
Then there’s the real estate side.
How quickly is your current home realistically likely to sell? What’s happening in the market where you want to buy? Are there plenty of homes that could work for you, or are you waiting for something very specific to come up?
That’s why I don’t think there’s a formula for this.
You look at your finances, your current home, what you’re hoping to buy and what the market is actually doing.
Then you make a plan that fits your situation.
And Sometimes the Plan Changes
This might be the most important part.
You can make a great plan before you start, and real estate doesn’t always cooperate.
I’ve had clients buy first thinking we’d sell their previous home relatively quickly, only to have the market tell us otherwise.
I’ve had other clients start out thinking they could buy without selling and discover along the way that we needed to restructure the purchase around a home sale contingency.
I’ve helped clients prepare everything ahead of time and successfully line up a sale and purchase.
And I have clients right now who aren’t forcing anything. They’re getting themselves ready and waiting for the house that makes moving worthwhile.
None of those approaches is wrong.
Sometimes we simply get new information and adjust.
That’s a big part of my job when I’m helping someone buy and sell at the same time. I’m not just helping you find a house or put a sign in your yard.
I’m looking several steps ahead and figuring out how all of these pieces can work together.
Frequently Asked Questions About Buying Before Selling
Can I make an offer on a house before mine is listed?
Yes. Whether that makes sense depends on your finances and whether your purchase needs to be contingent upon selling your current home. If it does, having your home ready to go on the market quickly can put you in a better position.
Is a home sale contingency difficult to get accepted in Massachusetts?
It can be, particularly when you’re competing against buyers who don’t have a home to sell. But every property and situation is different. Price, competition, days on market, the status of your current home and the rest of your offer can all make a difference.
What is a bridge loan?
A bridge loan is short-term financing that can help bridge the gap between buying your new home and selling your existing one. It can provide more flexibility, but bridge loans tend to be more expensive than traditional financing and aren’t right for everyone. A lender can help determine whether it’s an option for your particular situation.
Is it better to sell your house before buying another one?
Not necessarily. Selling first can give you more financial certainty, but it can also leave you needing temporary housing while you search. Buying first gives you more flexibility on the housing side but can mean carrying two properties. The better option depends on your finances, your market and what you’re trying to buy.
What happens if I sell before I find another home?
You’ll need a plan for the time between homes. That could mean renting, staying with family or friends, using another property or potentially negotiating some additional time in your existing home after closing. And sometimes selling first is intentional because you want time to decide where or what you want to buy next.
The Bottom Line
If you’ve been thinking about moving but keep getting stuck on:
“I can’t buy because I haven’t sold.”
Or:
“I can’t sell because I don’t know where I’m going.”
Don’t let that be the reason you do nothing.
You don’t necessarily need to know exactly how you’re going to make the move today.
Start by finding out what’s possible.
Talk with your lender. Get a realistic idea of what your current home could sell for. Pay attention to what’s actually available where you want to go.
Then you can build a plan around your situation.
And if the market changes the plan along the way?
You adjust.
If you’re thinking about making a move and aren’t sure how the buying and selling pieces could work together, I’m always happy to talk through the options with you.
Why Summer Is One of the Biggest Transition Seasons in Real Estate
The summer transition season in real estate always brings a noticeable shift in the market.
Right after Memorial Day, many buyers and sellers start thinking differently. Some families become more motivated to move before the fall, while others slow down, travel more, and put home searches on pause for a bit.
Quick Answer
The summer transition season in real estate is a time when lifestyle changes often drive housing decisions. Some buyers become more serious about finding a home before school starts, while some sellers benefit from motivated buyers and less competition as the season progresses.
What Is the Summer Transition Season in Real Estate?
The summer transition season in real estate is the period after Memorial Day when the market often shifts from the fast pace of spring into a more lifestyle-driven season.
Spring is usually about urgency:
- new listings
- busy open houses
- competitive offers
Summer feels different.
People travel more, kids finish school, and schedules become less predictable. However, some buyers become more motivated because they want to settle into a new home before September.
So while activity can slow in some ways, serious buyers are still very much out there.
According to the National Association of REALTORS® Research Center, seasonal timing continues to play a major role in buyer and seller behavior across the housing market.
What Changes During the Summer Transition Season in Real Estate?
One of the biggest changes is mindset.
I often see buyers become more intentional this time of year. By summer, many people have already spent months casually browsing online or visiting open houses. Now they’re starting to ask:
- Can we realistically move before school starts?
- Do we need more space?
- Is now the right time to make a change?
At the same time, some buyers pull back completely for a few weeks because life gets busy.
That’s why summer can feel both active and quiet at the same time.
For sellers, this creates an interesting opportunity.
Homes that are priced correctly and presented well can still perform very strongly because serious buyers have fewer homes to choose from later in the summer.
But overpriced homes often sit longer because buyers become more selective.
Why the Summer Transition Season in Real Estate Matters
This shift matters because timing affects strategy.
For buyers, summer can sometimes mean:
- slightly less competition
- more negotiating opportunity
- motivated sellers
- a chance to move before fall
For sellers, summer can still be an excellent time to list, especially if your home fits what families are actively searching for.
I’m seeing this right now with many move-up buyers. Families are realizing they’ve outgrown their current homes and want more functional space before another school year begins.
At the same time, some longtime homeowners are starting to think about simplifying life a little. Summer often gives people more time to reflect on what they want their next chapter to look like.
That emotional side of real estate is very real.
According to Freddie Mac Research, housing decisions are often tied closely to larger life transitions, family needs, and affordability changes.
What Today’s Buyers and Sellers Really Want in 2026
What This Means for Buyers and Sellers
For buyers, this is a reminder that summer isn’t “too late.”
In fact, some buyers find better opportunities once the intense spring competition settles down a bit.
For sellers, it’s important to understand that buyers become more selective during the summer months. Presentation, pricing, and marketing matter even more when people are balancing vacations, camps, and busy schedules.
I also think summer tends to make people picture lifestyle more clearly.
People start imagining:
- backyard barbecues
- walkable neighborhoods
- easier commutes
- hosting family and friends
- more space to enjoy everyday life
And honestly, those are often the things that push someone from casually looking to seriously moving.
Bottom Line
The summer transition season in real estate is less about hype and more about life changes.
Some buyers become highly motivated before fall. Others slow down and wait until later in the year.
But every summer, I see people start thinking more seriously about what they want their next chapter to look like—and real estate often becomes part of that conversation.
For additional housing and market research, the U.S. Census Bureau Housing Data also tracks national housing trends and migration patterns.
If you’re thinking about making a move this summer and want to talk through timing, strategy, or what the market is feeling like locally, I’m always happy to help.
What Today’s Buyers and Sellers Really Want in 2026
What today’s buyers and sellers really want in 2026 has less to do with trends and more to do with real life changes.
Right now, I’m seeing two groups driving a lot of the market: move-up buyers looking for more space and longtime homeowners looking to simplify and downsize.
Quick Answer
Many buyers and sellers in 2026 are making moves based on lifestyle changes, not just market conditions. Families are searching for homes that fit their next stage of life, while many downsizers are looking for easier, lower-maintenance living.
What’s Driving Today’s Market
A recent report from the National Association of REALTORS® found that Millennials and Gen X buyers continue to make up a large portion of today’s buyers, while many Boomers remain active sellers.
Honestly, that lines up exactly with what I’m seeing locally.
Many move-up buyers bought starter homes years ago. Now they need:
- another bedroom
- more functional space
- a better layout
- room for kids, work, or both
At the same time, many longtime homeowners are starting to think differently about what they want next.
For some, the goal is less maintenance.
For others, it’s first-floor living, being closer to family, or simply having a home that feels easier to manage.
Is It the Right Time to Move? 5 Signs You Might Be Ready
Why Buyers Are Moving Up in 2026
Move-up buyers are still very active right now, especially families who have built equity in their current homes.
I’m seeing many buyers focus less on finding a “dream house” and more on finding a home that works better for everyday life.
Things like:
- mudrooms
- home offices
- bigger yards
- updated kitchens
- flexible living space
matter more than ever.
According to the report, older Millennials purchased some of the largest homes among all buyer groups.
That makes sense because many buyers in this stage of life are balancing growing families, careers, and long-term planning all at once.
Why Downsizers Are Moving in 2026
Downsizing looks different for everyone.
Some homeowners want a condo or smaller property with less upkeep. Others still want space, but without the maintenance of a larger home.
I recently spoke with a homeowner who has loved their house for years, but keeping up with everything has started to feel like more work than enjoyment. Instead of waiting until it becomes overwhelming, they’re starting to think ahead now.
That’s something I’m hearing more often lately.
The same NAR report found that older buyers were more likely to purchase condos, duplexes, and senior-related housing.
And honestly, many of those moves are about lifestyle, not downsizing financially.
What This Means for Buyers and Sellers
This shift matters because buyers today are shopping differently.
People are thinking more carefully about:
- how long they’ll stay
- how they actually use their space
- what daily life looks like in a home
For sellers, it’s a reminder that different buyers value different things.
A young family may love extra bedrooms and a playroom. A downsizer may care more about updated systems, fewer stairs, or walkability.
That’s why presentation and marketing matter so much. The same home can appeal to completely different buyers depending on how it’s positioned.
Bottom Line
Today’s market is being shaped by people making thoughtful life changes.
Some buyers need more space.
Some homeowners want less maintenance.
Others are simply looking for a home that fits their life a little better right now.
And honestly, that’s what real estate has always been about.
For more housing trends and research, the National Association of REALTORS® Research Center and Freddie Mac Research both provide helpful consumer-focused data.
Milton Election Day: What Residents Should Know Before Voting
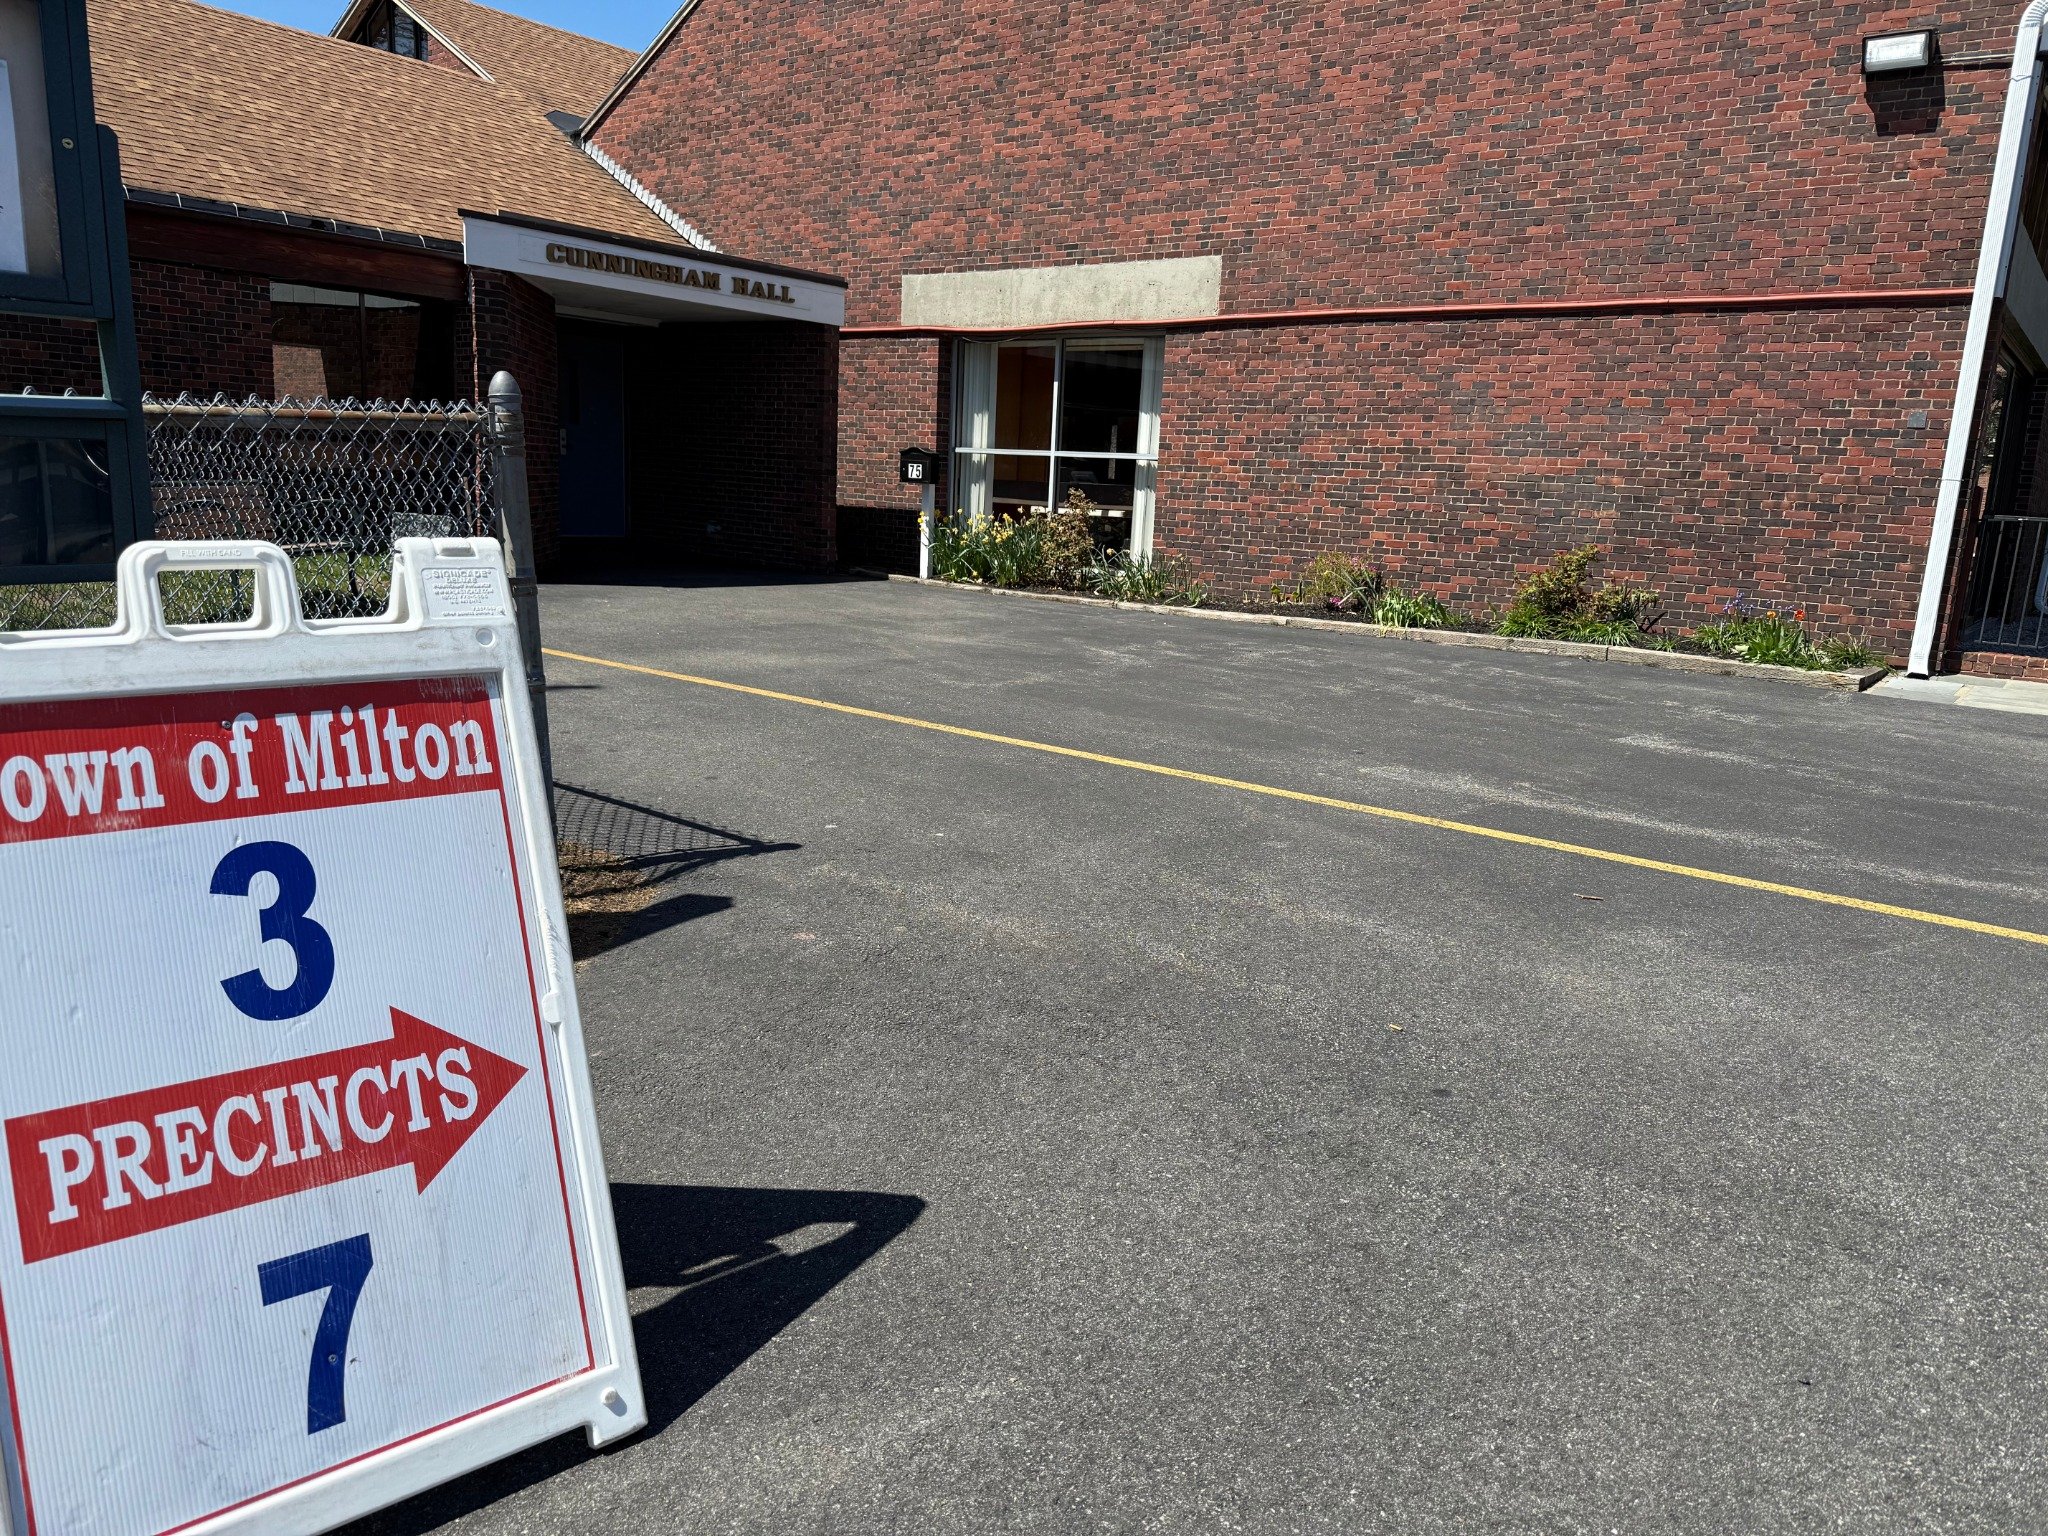
Milton Election Day is here, and it’s a good moment to take a step back and understand what’s on the ballot and why it matters for our community.
Whether you’ve been here for years or just moved to town, local elections play a bigger role in day-to-day life than most people realize.
Quick Answer
Milton Election Day is when residents vote on local leadership and decisions that directly impact schools, taxes, housing, and the overall direction of the town.
What Is Milton Election Day?
Milton Election Day is when residents vote for local positions that help shape how the town is run.
These roles often include:
- Select Board
- School Committee
- Planning Board
- Other town positions depending on the year
You can find official ballot details and voting information through the Town of Milton.
While these elections may feel smaller than national ones, they often have a more direct impact on everyday life.
How Milton Election Day Works
Local elections are typically decided by a smaller group of voters, so each vote carries more weight.
Depending on the ballot, you may see:
- contested races (multiple candidates)
- uncontested positions
- town questions or measures
For the most accurate and up-to-date list of candidates and ballot items, it’s always best to refer directly to Town of Milton official resources.
Why Milton Election Day Matters
Milton Election Day matters because local decisions affect things people care about every day.
For example:
- school funding and resources
- property taxes
- zoning and development
- town services and infrastructure
According to data from the U.S. Census Bureau, local governance plays a key role in how communities grow and how resources are allocated.
So while it may not always get the same attention, it has real impact.
What This Means for Buyers and Sellers
This is where it connects more directly to real estate.
Buyers often ask about:
- school systems
- taxes
- long-term development
And those are all shaped at the local level.
I’ve had buyers specifically choose Milton because of the community feel, the schools, and how the town is managed overall. Those things don’t happen by accident—they’re influenced by the people and decisions made locally.
For sellers, a strong and well-run town can:
- attract more buyers
- support home values
- create confidence in the market
So even though this is a local election, it ties back to how people experience living here.
A Personal Note
As someone who both lives and works in Milton—and is raising my kids here—this day always feels important.
It’s not just about voting. It’s about being part of the community and helping shape the place we call home.
Bottom Line
Milton Election Day is a chance to have a voice in the decisions that shape daily life in town.
Even small local elections can have a lasting impact, so it’s worth taking a few minutes to understand what’s on the ballot and participate.
If you have questions about how local decisions tie into the housing market or what people are looking for when moving to Milton, I’m always happy to talk through it.
How New Condo Lending Guidelines Affect Buyers and Sellers in 2026
The new condo lending guidelines are changing how buyers and sellers approach condo purchases in 2026, so it’s something you’ll want to understand early.
If condos are on your radar this year, there’s an important shift happening behind the scenes. These updates are changing how lenders evaluate condo buildings, and that can directly impact whether a deal moves forward smoothly.
This actually came up recently with a buyer I’m working with. They found a condo they loved, but before getting too far, we had to pause and ask: Will this building even qualify for financing? That question is becoming more common.
Quick Answer
The new condo lending guidelines make it easier to finance some condos—especially smaller or investor-heavy buildings—but they also require stronger HOA finances, higher reserves, and more thorough insurance coverage.
What Are the New Condo Lending Guidelines?
The new condo lending guidelines are updated rules from Fannie Mae and Freddie Mac that lenders use to decide whether a condo qualifies for a mortgage.
These updates are largely in response to:
- rising insurance costs
- underfunded HOA reserves
- deferred maintenance concerns
According to the National Association of Realtors, lenders are placing more emphasis on the overall financial health of condo associations—not just the individual unit.
👉 In simple terms: buying a condo now means buying into the building’s financial story, too.
What’s Changed with the New Condo Lending Guidelines?
Easier Approvals in Some Cases
There is some good news here.
- Smaller condo projects (2–10 units) may have an easier path to approval
- Investor-heavy buildings are facing fewer restrictions
- Some of the older, more complicated review processes have been simplified
So yes—there are more opportunities in certain types of buildings.
Stronger HOA Financial Requirements
At the same time, the new condo lending guidelines are more strict where it matters most.
- Reserve requirements are increasing (from 10% to 15%)
- Reserve studies must reflect realistic funding needs
- Deferred maintenance and structural concerns are under greater scrutiny
This is where deals can get tricky.
A building might look well-maintained, but if the numbers behind it aren’t strong, it can impact financing.
Insurance Is Now a Bigger Factor
Insurance has become a key part of condo approvals.
- More flexibility in how coverage is evaluated
- Caps on deductibles
- Greater importance placed on HO-6 (unit owner) policies
This is largely due to rising insurance costs across the country, something highlighted in housing data from organizations like the U.S. Census Bureau.
Why the New Condo Lending Guidelines Matter
The new condo lending guidelines matter because they can affect:
- whether a buyer qualifies for financing
- how smooth (or stressful) a transaction is
- whether a condo is even eligible for purchase with a loan
I’ve seen buyers get all the way to the offer stage before realizing the building itself creates a hurdle. That’s the kind of situation we want to avoid upfront.
What This Means for Buyers and Sellers
For Buyers
There may be more flexibility in some condo options, but there’s also more due diligence required.
You’re not just evaluating:
- the unit
- the layout
- the location
You’re also looking at:
- HOA reserves
- building maintenance
- insurance coverage
This is where asking the right questions early can make all the difference.
For Sellers
If you own a condo, your association’s financial health is now part of your home’s story.
Stronger finances can:
- help attract more buyers
- reduce financing issues
- lead to smoother closings
On the flip side, weaker financials can create delays—even if your unit shows beautifully.
A Real-Life Perspective
I sat down with Ruby Santos, a lender at Guaranteed Rate Affinity, to talk through what she’s seeing firsthand about these changes.
Hearing it directly from a lender really brings this into focus—especially when it comes to how deals are being approved (or not) right now.
Bottom Line
The new condo lending guidelines are creating a shift—not a stop.
Some condos will be easier to finance. Others will require a closer look.
Understanding that difference early can save time, stress, and unexpected surprises along the way.
If you’re not sure how a specific building stacks up, I’m always happy to walk through it with you so you feel confident moving forward.
Tommy’s Place: Bringing Joy to Families Facing Childhood Cancer
Some organizations stay with you. For our family, Tommy’s Place is one of those places.
Not just because of what they do, but because of how they make people feel during some of the hardest moments in life.
What Is Tommy’s Place?
Tommy’s Place is a nonprofit that welcomes children battling cancer and their families for special stays in Falmouth and Centerville.
It gives families something incredibly meaningful. Time to step away from hospital visits and treatment schedules and instead focus on being together.
It is not about medical care. It is about creating space for joy, connection, and lasting memories during an incredibly difficult time.
Why Tommy’s Place Means So Much to Our Family
Emily was a dear friend of our family and the same age as our youngest daughter, Claire.
They met at the hockey rink, cheering on their older sisters, and quickly became inseparable. Not long after, they were in the same kindergarten class, where their friendship continued to grow.
In 2021, Emily was diagnosed with leukemia.
During her incredibly brave fight, her family was invited to spend a week at Tommy’s Place. That experience gave them something every family deserves during a time like that. A chance to simply be together, to laugh, and to create joyful memories in the middle of something so hard.
When I once asked Emily which organization she would choose to support, out of all the places that had helped her, she didn’t hesitate.
She chose Tommy’s Place.
Emily passed away in February 2024, and she remains very much a part of our lives and our hearts.
How We Continue to Support This Mission
Since then, we have found ways to give back to an organization that meant so much to her.
Through Boston Women Rising, I nominated Tommy’s Place for a grant.
We have also spent time volunteering at the homes, helping prepare them for the next families arriving each week. Everything is fully volunteer-driven, 52 weeks a year, which makes it even more meaningful to be a small part of what they do.
Last year, Caroline and I ran the Falmouth Road Race in Emily’s honor.
This year feels even more special. Claire is now old enough to join us, and the three of us will be running together for Emily.
Why Tommy’s Place Matters
Organizations like this fill a space that is hard to put into words.
They give families a break from the clinical side of cancer and replace it with something lighter, even if just for a little while.
Moments of normalcy
Time together
Space to just be a family
Those experiences matter more than people often realize.
How You Can Support This Mission
If you are looking for a way to make a difference, this is one that has a very real impact.
Supporting Tommy’s Place helps more families experience the same sense of joy and connection that meant so much to Emily and her family.
Whether that is through donating, sharing their mission, or simply learning more about what they do, every bit of support helps. If you’d like to support our fundraising efforts in Emily’s honor, I’ve included a link at the end of this post.
The Bottom Line
Some causes become personal, and Tommy’s Place is one of those for our family.
Running the Falmouth Road Race is our way of honoring Emily and supporting a place that gave her family such a meaningful gift during an incredibly difficult time.
If this story resonates with you, we would love your support. Click to support our Tommy’s Place fundraiser for Emily.
Even simply sharing their mission or keeping Emily’s spirit in mind truly means a lot.
Frequently Asked Questions
What is Tommy’s Place?
Tommy’s Place is a nonprofit that provides special stays for children battling cancer and their families, focused on creating joyful and meaningful experiences.
How does Tommy’s Place help families?
It gives families time away from treatment environments so they can focus on connection, rest, and making positive memories together.
How can I support Tommy’s Place?
You can support through donations, volunteering, or helping spread awareness about their mission.
Sources
Tommy’s Place Official Website
https://tommysplace.org
American Cancer Society
https://www.cancer.org
